Can Home Equity Help You Catch Up on Missed Mortgage Payments?

See how Arizona homeowners with substantial equity may be able to use the strength of the property to address mortgage arrears.
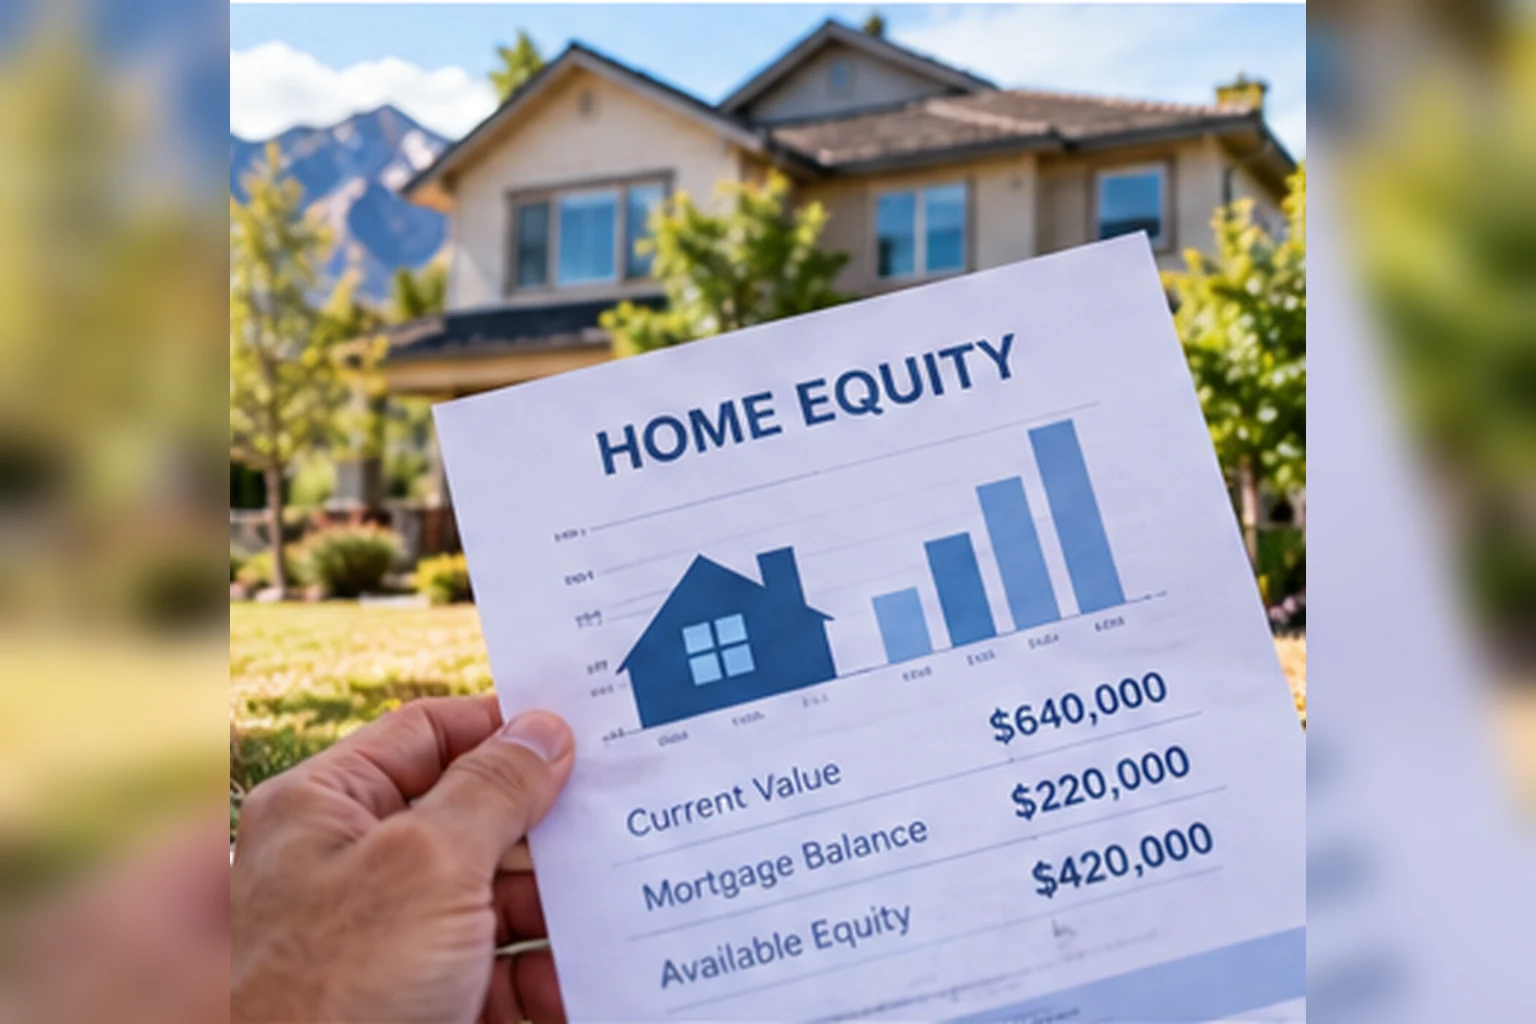
Arizona homeowners reviewing mortgage and home equity options

Your home can be valuable even when cash is tight

A homeowner may have built significant wealth in a property while having very little cash available today. That is common after a temporary income disruption or unexpected expense.

Calculate the equity before deciding what to do

Subtract the approximate balances of mortgages and other liens from a realistic property value. A $700,000 home with $455,000 in total liens has roughly $245,000 in equity before transaction costs or other adjustments.

Compare the equity with the amount needed

If that same homeowner needs $28,000 to bring the mortgage current, selling a $700,000 asset is not automatically the only answer. The immediate need represents only a fraction of the property’s approximate equity.

Why credit can complicate traditional borrowing

Recent mortgage lates can lower credit and make a conventional HELOC or refinance harder. Private equity-based financing can be evaluated differently, with more emphasis on the collateral and available equity.

What approximately $100,000 in equity means for our review

The strongest candidates for the type of assistance discussed here generally have around $100,000 or more in available equity. More equity can provide more room to solve arrears while protecting the homeowner’s remaining position.

The goal is not to use all of your equity

The point is not to cash out everything you have built. The question is whether accessing enough equity to solve the immediate arrears could be preferable to losing or selling the entire property.

Use the property to evaluate the problem

If you can afford the regular mortgage going forward but cannot overcome accumulated arrears, submit the property value, balances, cure amount and foreclosure date for review. The equity may change what is possible.

Request a private property review

If you want to keep your Arizona home and have substantial equity, send us the approximate property value, mortgage balances, amount you are behind and any foreclosure sale date. Situations with approximately $100,000 or more in available equity are generally the best fit for the type of assistance we provide.

Request a private property review

If you want to keep your Arizona home and have substantial equity, send us the approximate property value, mortgage balances, amount you are behind and any foreclosure sale date. Situations with approximately $100,000 or more in available equity are generally the best fit for the type of assistance we provide.

Tell us about your home

Arizona Foreclosure FAQ

How many months behind before foreclosure in Arizona?

For most covered mortgages, federal servicing rules generally prevent the first foreclosure notice or filing until the loan is more than 120 days delinquent, roughly four months; exceptions apply. Arizona then requires a separate trustee-sale notice period: under A.R.S. § 33-808, the auction date can be no sooner than the 91st day after the Notice of Trustee’s Sale is recorded. This is often described as a 90-day minimum notice window. These are separate stages, not a guaranteed auction date based on a fixed number of missed payments. Servicing requirements, postponements, and case-specific circumstances may extend the process.

When is the absolute cutoff to cure my default in Arizona?

For a qualifying default accelerated before the loan’s scheduled maturity, A.R.S. § 33-813 permits reinstatement before 5:00 p.m. Mountain Standard Time (MST) on the last day other than a Saturday or legal holiday before the trustee sale, commonly described as the last business day before the sale. Cure requires the amounts then due, permitted costs and fees, and correction of other defaults, excluding principal due only because of acceleration. Obtain a written reinstatement quote and acceptable payment instructions from the trustee early. Payment must be completed before the cutoff; requesting a quote does not extend it. Confirm the precise deadline and sale cancellation with the trustee.

Are private foreclosure bailout loans available in Arizona?

Private home-equity financing may be available to eligible Arizona homeowners facing foreclosure. Sometimes called foreclosure bailout loans, these are repayable loans secured by the home, not grants or guaranteed relief. Depending on the transaction, a new home-equity lien may fund mortgage arrears and reinstatement costs, or refinancing may pay off the foreclosing loan. Approval depends on available equity, title and lien priority, repayment ability, costs, and time to close. Funding and payment must be completed by the applicable deadline for reinstatement or payoff to stop the trustee sale. Missed payments on the new loan can put the home at risk. An inquiry or preliminary approval does not itself stop or postpone foreclosure.

Sources: 12 CFR 1024.41(f), A.R.S. § 33-808, and A.R.S. § 33-813. Read the Arizona Foreclosure Timeline & Reinstatement Guide for more detail.

General educational information, not legal advice. Residential Capital, LLC reviews each situation individually. Financing is subject to approval and does not guarantee foreclosure relief. Submitting an inquiry does not stop or extend foreclosure deadlines.